Singapore’s logistics property market has a fresh transaction to watch. JD Property and EZA Hill have acquired four logistics properties from CapitaLand Ascendas REIT (CLAR), adding another data point to the city-state’s tightly held warehouse sector.
The deal matters less for its headline value than for what it says about buyer selectivity. Well-located facilities with efficient loading, modern specifications and access to established transport corridors continue to attract capital, even as investors remain careful about pricing and financing.

Why the portfolio is significant
Portfolio trades give buyers a quicker route into Singapore’s industrial ecosystem than acquiring individual buildings one at a time. They also provide operating scale: leasing, maintenance and tenant relationships can be managed across several assets, while different building profiles spread concentration risk.
For sellers such as CLAR, a portfolio disposal can recycle capital into new acquisitions or development opportunities. CLAR’s recent results have already highlighted the importance of logistics and industrial assets in its regional strategy; our earlier coverage of its 1H 2026 results provides that wider context.
What buyers will examine next
- Tenant quality and lease expiry: stable cash flow is valuable, but upcoming renewals can change the risk profile.
- Building efficiency: ramp-up access, floor loading, ceiling height and power availability affect occupier demand.
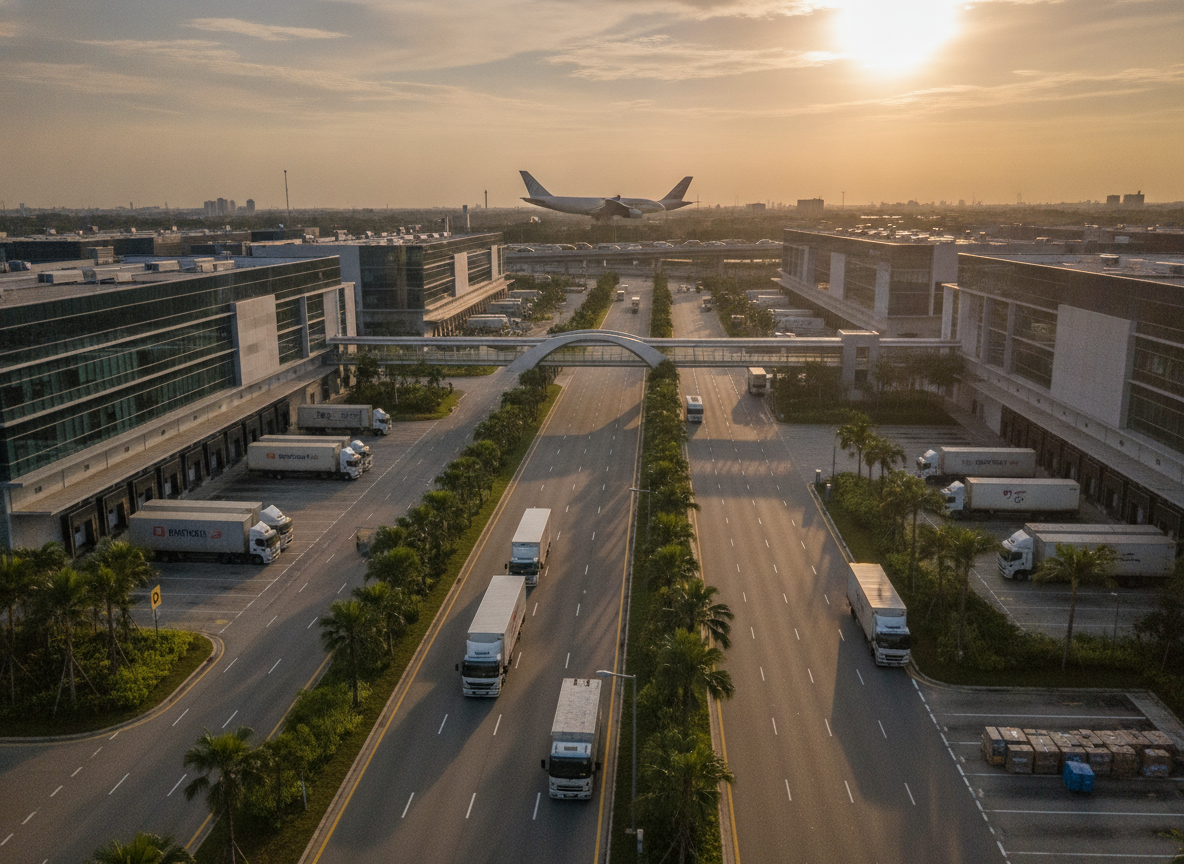
- Location resilience: proximity to ports, airports and expressways can support distribution users when delivery networks are under pressure.
- Future capital needs: older assets may require upgrades for energy performance, automation or fire-safety compliance.
Implications for Singapore’s industrial market
This transaction should not be read as a blanket signal that every warehouse will command a premium. Instead, it reinforces a two-speed market. Modern, accessible facilities can benefit from resilient demand, while buildings with weaker specifications may need sharper pricing or targeted refurbishment.
Owners and occupiers can use the deal as a prompt to benchmark their own assets: compare rents, vacancy, remaining lease term and transport access rather than relying on broad market averages. Readers tracking the region’s logistics direction can also see how ASEAN supply-chain investment is developing, while our Tuas logistics hub report looks at a separate west-side opportunity.
For now, the message is measured but constructive. Singapore remains a scarce industrial market, and professionally managed logistics assets are likely to stay on institutional investors’ radar. The next test will be whether occupier demand and rental income continue to justify the prices buyers are prepared to pay.

